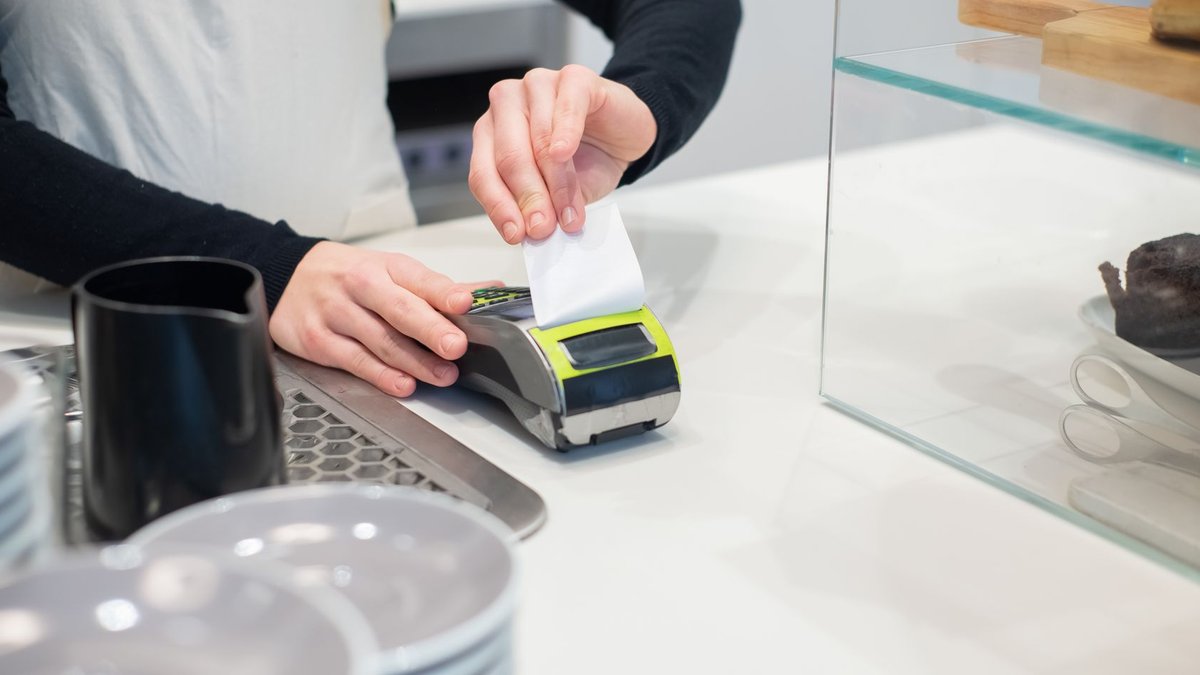
When a consumer pays for a product or service at a commercial establishment, they may occasionally receive a duplicate charge on their debit or credit card. The problem can be even more significant when the individual notices the duplicate charge, complains to the merchant or bank, and, despite presenting transaction receipts, does not receive a refund.
The main question in these cases is who is responsible for the excess charge and what they can do to recover it. The responsibility will depend on where the error originated: whether it was a duplicate charge made by the establishment, a failure in the datáfono, or an issue with the financial institution’s processing of the transaction.
Consumer Rights
Daniela Melo, a lawyer at Centro Jurídico Internacional, explained that when a consumer is charged twice, they have the right to verbally request the establishment to refund the excess amount, as well as any associated costs, such as commissions or management fees.
The attorney added that consumers can also file a formal complaint directly with the establishment or the financial institution and request transaction receipts, such as sales receipts, vouchers, or registros del datáfono. Keeping copies of all documentation is recommended, because it strengthens the case if the dispute escalates.
Formal Complaints
If none of the above actions are effective, the consumer can file a complaint or lawsuit with the Superintendencia de Industria y Comercio (SIC) or seek help from the Defensoría del Consumidor Financiero del banco emisor, according to Melo.
Read Also: Best Lawyers names top attorneys in Colombia
In cases where this is a repeated practice, Diego Andrés Navarro Rangel, a lawyer specializing in administrative law, noted that the SIC could impose sanctions on commercial establishments, including fines, temporary closure, or even permanent closure, after conducting an administrative investigation.
Sanctions and Fines
According to Ley 1480 de 2011, article 61, fines can be up to 2,000 salarios mínimos mensuales legales vigentes, and establishments can be temporarily or permanently closed. Navarro emphasized that the repetition of these behaviors, lack of response, and unjustified refusal to refund the money can be relevant factors in determining responsibility.
In the case of financial institutions, they are also subject to a special consumer protection regime. If a bank fails to comply with its legal obligations, provides deficient services, or disregards unjustified complaints, it can be investigated and sanctioned by the Superintendencia Financiera de Colombia, according to the same lawyer.
Refund Process
Melo indicated that after a formal complaint, the establishment has 15 business days to respond. However, in commercial practice, many establishments and banks correct duplicates by processing cancellations within 24 to 72 hours if the complaint is made immediately.
Navarro emphasized that a duplicate charge, in itself, does not automatically imply a sanction. The authorities must investigate the facts and determine if there was an infringement.

Leave a Reply