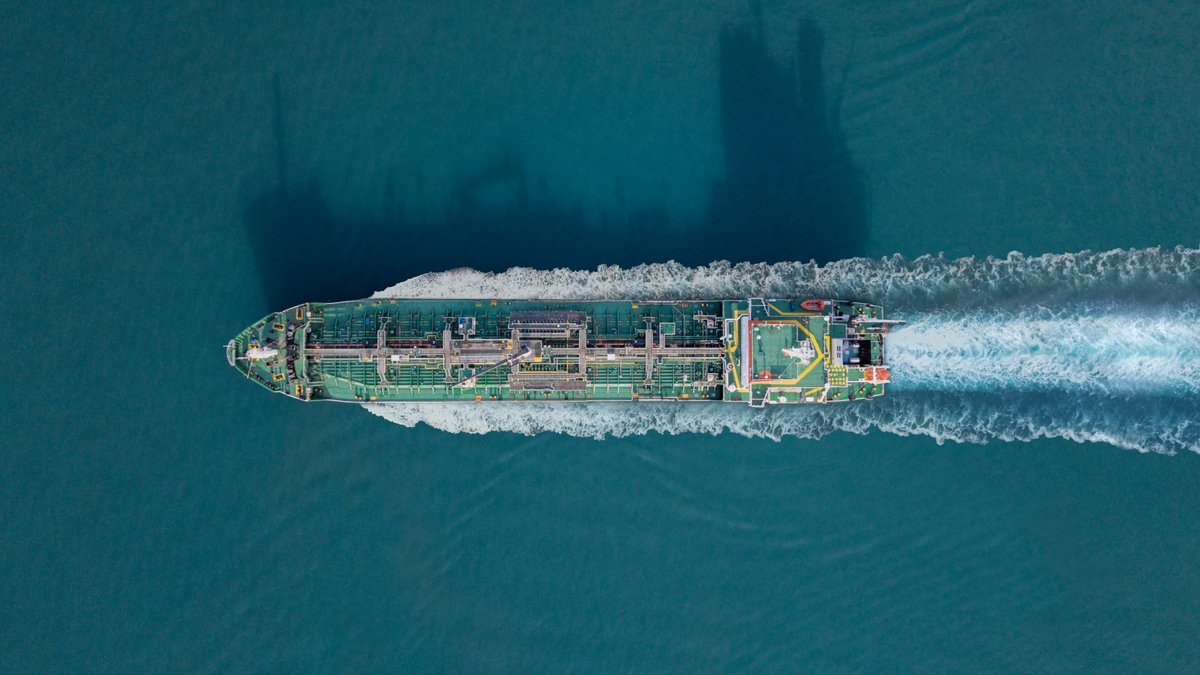
Global infrastructure mergers and acquisitions slowed in 2025, with deal value dropping from roughly US$28 billion in 2024 to US$22 billion and completed transactions falling from fifty-one to forty. While tighter financing and macro uncertainty contributed, the Strait of Hormuz has emerged as a focal point for investors seeking strategic resilience.
Ports are no longer seen merely as transport nodes. Recent disruptions—including the COVID-19 pandemic, the Red Sea crisis, and heightened tensions in the Hormuz corridor—have showed their role as critical links in global supply chains, energy security, and national defense.
Investment committees have adjusted their questions. Earlier deals chased higher container throughput and EBITDA growth. Today, buyers ask how a potential acquisition would mitigate concentration risk and sustain operations if a major trade route were blocked.
The legal mechanics of cross-border deals remain unchanged; share purchase agreements, due diligence, and valuation models are still the core tools. However, the strategic importance of ports means those tools are applied with heightened attention to geopolitical risk.
Valuation and Due Diligence Shift
Traditional valuations still prioritize projected cash flows, concession length, and regulatory environment. Yet strategic buyers now assign a premium to assets that diversify a portfolio away from vulnerable corridors, such as the Hormuz Strait, even if standalone financial metrics are modest.
Legal due diligence traditionally examined assets, contracts, permits, and litigation. When resilience drives the transaction, buyers also assess whether the target reduces geographic concentration and enhances network flexibility, extending analysis beyond the target’s own liabilities.
For operators, this shift means that the primary justification for a purchase may be to secure alternative trade lanes rather than to boost immediate earnings. By anchoring assets in regions less exposed to maritime chokepoints, they can safeguard revenue streams against sudden disruptions.
Regulators are expanding foreign direct investment screening, especially for critical infrastructure. In the United States, CFIUS reviews now cover certain non-controlling stakes in ports, reflecting the broader view that ownership can affect national security.
Transaction Structuring and Risk Allocation
Geopolitical uncertainty prompts parties to favor phased investments, joint ventures, or minority stakes that preserve flexibility. Pairing a port operator with a sovereign wealth fund can spread balance-sheet risk and ease approval under tighter FDI regimes.
Material adverse change clauses are being renegotiated to capture sanctions, trade route disruptions, or sudden cost spikes. Parties decide whether such events trigger a MAC provision or remain the buyer’s ordinary market risk, influencing post-closing indemnities.
In a recent announcement, DP World disclosed plans to develop a port and logistics hub in Fujairah on the United Arab Emirates’ east coast, a location deliberately outside the Strait of Hormuz corridor.
Foreign Investment Screening and Governance
The 2018 FIRRMA amendment may bring certain noncontrolling investments in U.S. businesses involved in critical infrastructure under CFIUS review.
Shareholder agreements may incorporate reserved matters that protect strategic expansion initiatives. Parties may agree that board composition includes representatives from the investor and the host sovereign, ensuring oversight of critical decisions.
Co-investment Models and Risk Management
Operators may structure transactions alongside sovereign wealth funds. This model may allocate balance-sheet exposure while offering a partner with state backing that may ease FDI clearance.

Leave a Reply